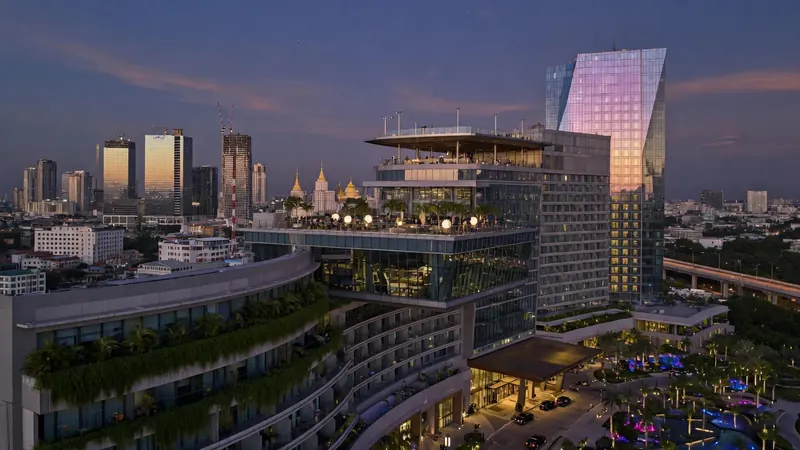
Las Vegas Sands Corp. is scheduled to report third-quarter 2026 financial results after the U.S. market closes on Oct. 21. Wall Street consensus calls for earnings of $0.77 per share and revenue of about $3.4 billion, according to two Yahoo Finance previews published Oct. 16. The earnings estimate implies a small year-over-year decline, while the revenue forecast points to a modest increase, making gaming demand in Singapore and Macao the main story.
Consensus earnings and revenue estimates
In the first Yahoo Finance preview, the Zacks Consensus Estimate for third-quarter EPS is 77 cents, down 1.3% from 78 cents a year earlier. The revenue consensus mark is pegged at nearly $3.4 billion, a 2.2% increase from the year-ago quarter. A second preview put the analyst consensus at $0.77 per share and $3.4 billion in revenue, with the revenue gain described as 2.1% year over year. That article also noted that the consensus EPS estimate has remained unchanged over the last 30 days. Las Vegas Sands has beaten the Zacks Consensus Estimate in three of the trailing four quarters and missed once, with an average earnings surprise of 8.5%.
Marina Bay Sands segment projections
For Marina Bay Sands, the collective analyst forecasts include net revenues of $1.41 billion, a decline of 1.8% from the prior-year quarter. The property is expected to post rolling chip volume of $9.42 billion, up from $9.07 billion a year earlier, and non-rolling chip table games drop of $2.75 billion, up from $2.55 billion. Analysts also project a rolling chip win percentage of 4.2%, below the 4.8% reported in the same quarter of the previous year. A separate article described the Singapore property as a likely growth driver, benefiting from demand among wealthy visitors and the property's expanded premium suites. Management has said that renovated suites, better service and improved gaming options have lifted the property's earnings potential.
Macao property-level projections
Wall Street's consensus for The Venetian Macao is $671.82 million in net revenues, down 2.9% year over year. The Plaza Macao and Four Seasons Macao segment is expected to generate $208.23 million, up 1.1%, and Sands Macao $80.83 million, up 12.3%. A Zacks model cited in the first article projected overall Macao revenues to rise 5% to $2 billion, but estimated Plaza Macao and Four Seasons Macao revenues would fall 20.4% to $163.9 million. Las Vegas Sands' Macao operations are expected to have benefited from improving gaming volumes, market-share gains in premium mass and VIP, and investments in customer service, expanded table hours and upgraded hospitality offerings at The Londoner Macao and Four Seasons.
Margin and expense considerations
Macao's premium gaming market competition and higher customer reinvestment requirements are likely to have pressured margins. Renovations at The Venetian Macao may have limited room availability, and shifts in gaming hold rates and high-value patron visitation could have added volatility. Continued spending on service enhancements may have further weighed on profitability, although management expects operating expense growth to moderate in the second half of 2026. Zacks' model projects total operating expenses to increase 1.2% year over year to $2.64 billion in the third quarter.
What to watch on Oct. 21
Investors will compare reported results with the consensus estimates and watch for actual revenue by segment, gaming volumes and win rates. Because estimates are not guarantees, the Oct. 21 report may show material differences from these projections, particularly if hold rates or high-value visitation deviated from analyst assumptions. Las Vegas Sands has not issued public guidance for these specific figures; the consensus represents the average of estimates compiled by Zacks and other analysts.